TGS issued a correction to its third-quarter 2026 earnings release on October 22, adding Note 12 and stating that everything else remained unchanged. The TGS Q3 results showed revenue growth driven by high contract activity, but operational challenges and low contract pricing weighed on margins.
Key Takeaways
- Revenue rose to $397 million from $388 million a year earlier, while EBITDA and EBIT declined despite a $41 million business-sale gain.
- Order backlog reached $679 million, up 52% year over year, with the streamer fleet fully booked for the fourth quarter.
- TGS lowered expected 2026 multi-client investment to approximately $510 million from approximately $550 million as it deferred certain projects.
Table of Contents
- TGS Q3 results show earnings pressure despite higher activity
- Backlog grows as management sees a stronger pipeline
- Project deferrals lower investment outlook
- Conclusion
TGS Q3 results show earnings pressure despite higher activity
Third-quarter EBITDA was $222 million, compared with $242 million in the same period of 2025. EBIT fell to $86 million from $94 million. Both current-quarter measures included a $41 million gain from the sale of the well data business.
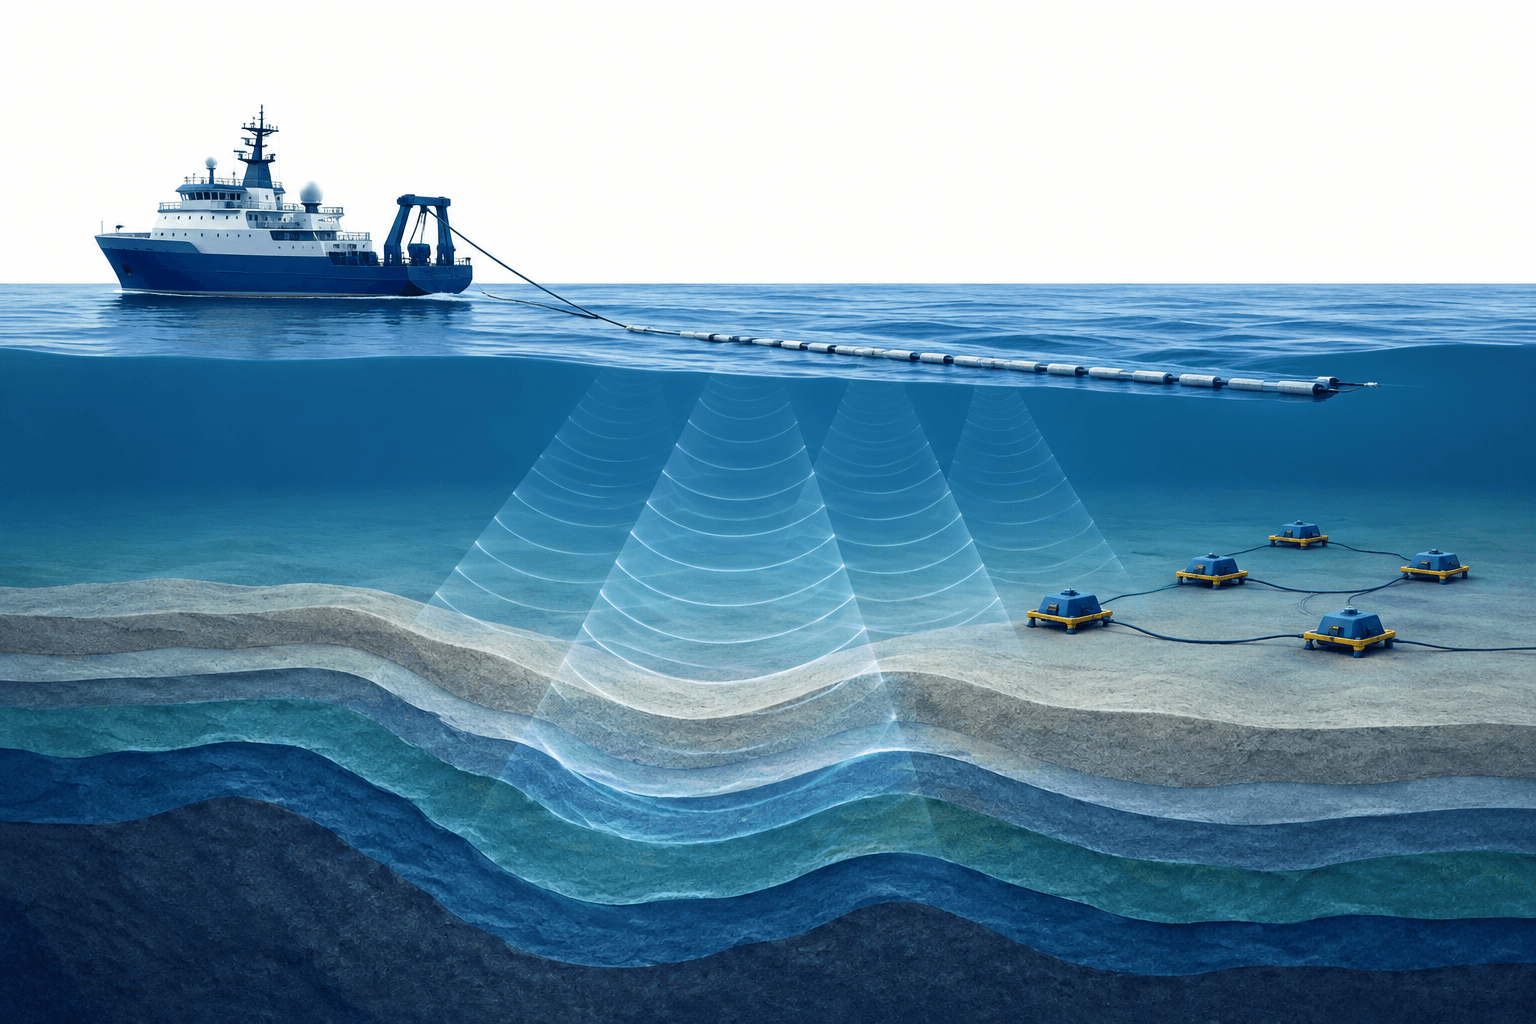
Chief Executive Kristian Johansen said strong activity across the 3D streamer vessel fleet and Ocean Bottom Node operations produced the highest contract revenue since the fourth quarter of 2024. However, higher costs arising from operational challenges, together with low contract pricing, hurt margins.
The correction notice identifies the addition of Note 12 as the only change. The supplied report does not reproduce that note's contents.
Backlog grows as management sees a stronger pipeline
TGS reported order inflow of $357 million, bringing total backlog to $679 million. Both figures exclude the North American well data business, which was sold during the third quarter of 2026.
Johansen said new contract awards and multi-client projects supported order intake. With the streamer fleet fully booked for the fourth quarter, he said visibility had improved significantly from a year earlier, allowing the company to optimize asset allocation.
Management also reported a stronger pipeline of streamer contract opportunities, including occasions when clients competed for available capacity. Johansen said this supported his confidence that contract pricing would improve from 2027. Increasing Ocean Bottom Node tendering activity reinforced the company's expectation of higher activity in 2027; these remain management expectations rather than completed outcomes.
Project deferrals lower investment outlook
TGS decided to defer certain multi-client projects because of the increased volume of contract work in its pipeline. It now expects multi-client investments of approximately $510 million in 2026, down from previous guidance of approximately $550 million.
The company also reported a dividend of $0.155 per share to be paid in the fourth quarter of 2026.
Conclusion
The corrected release leaves TGS's reported financial picture unchanged: stronger revenue and backlog alongside lower earnings. Management expects improving contract opportunities, while shifting some planned multi-client investment to accommodate contract work.
Read More News
Disclaimer
This FinanceVelix article provides general information, not personalized financial, investment, legal, or tax advice. Market prices, interest rates and economic conditions can change; investments carry a risk of loss. Facts reflect the material available when published and may change. Check important information independently and consult a qualified professional when needed. Mentioning an asset, company, or service is not an endorsement.



