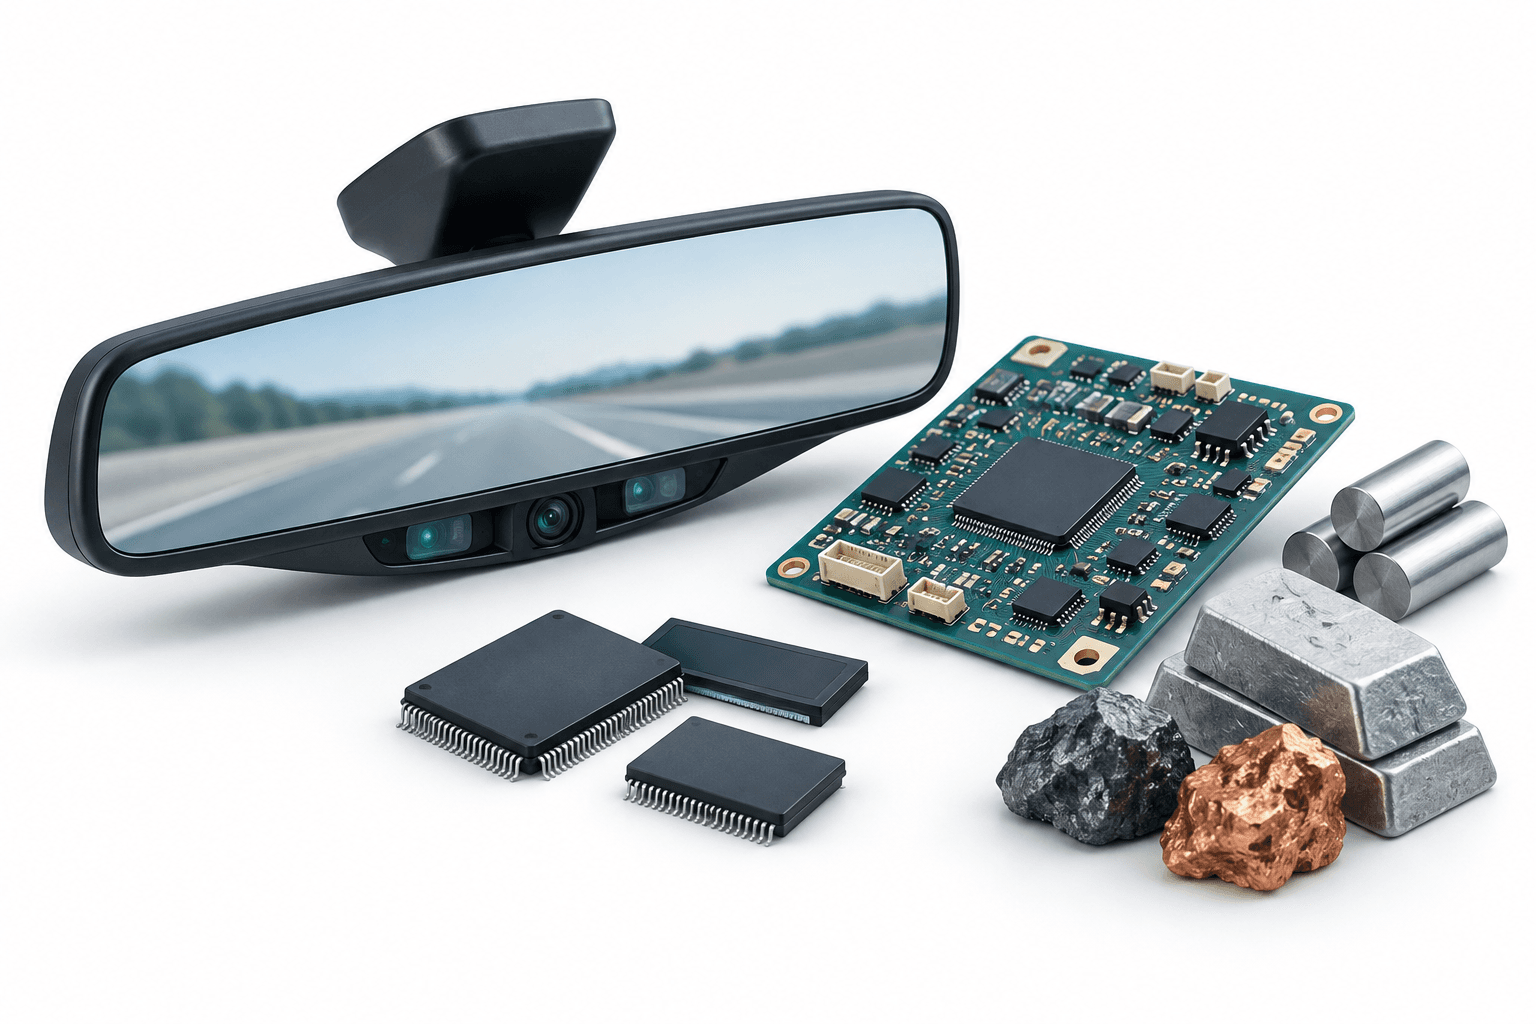
The Gentex outlook for 2027 remained at $2.8 billion–$2.9 billion in revenue after third-quarter 2026 sales fell short of management’s expectations. During the October 23 earnings call, executives pointed to new product launches and monitoring-system awards as growth drivers, while warning that rising electronics and precious-metals costs would pressure margins.
Key Takeaways
- Management maintained its 2027 revenue outlook, implying approximately 6%–9% growth over updated 2026 guidance.
- Third-quarter sales missed the beginning-of-quarter forecast by about $35 million amid customer disruptions and delayed launches.
- Component inflation remains a margin risk, with $10 million–$15 million of incremental costs expected in the fourth quarter.
Table of Contents
- Gentex outlook rests on launches and monitoring awards
- Electronics inflation complicates the margin picture
- Quarterly results show the cost of weaker automotive sales
- New manufacturing award has a longer timetable
- Conclusion
Gentex outlook rests on launches and monitoring awards
Chief Executive Officer Steven Downing described the third-quarter revenue shortfall as largely tied to one-time customer issues. He cited a Hyundai Kia union strike that removed 60,000–70,000 vehicle units and a later-than-expected F-250/350 launch with lower volumes.
For 2027, Downing pointed to further Full Display Mirror growth, additional in-cabin and driver-monitoring awards, and a distribution agreement between the VOXX team and Alpine. Management’s plan assumes China remains broadly stable, with some further headwinds rather than a recovery.
Gentex’s driver and cabin monitoring technology uses mirror-integrated cameras to assess driver alertness and gaze, while in-cabin systems track occupants and passenger activity. Those functions explain the products behind some of the anticipated growth; they do not establish the timing or value of future awards.
| Item | Details |
|---|---|
| 2026 revenue guidance | Approximately $2.65 billion. |
| 2026 gross-margin guidance | 34%–34.5%. |
| 2026 operating-expense guidance | $395 million–$410 million, excluding severance and impairments. |
| 2026 effective tax-rate guidance | 16%–16.5%. |
| 2026 capital-expenditure guidance | $100 million–$115 million. |
Electronics inflation complicates the margin picture
Downing offered an explicitly preliminary estimate of 33%–34% for 2027 gross margin, warning that electronic supply constraints could push the outcome below that range. He said growth and new launches could partly offset higher material costs through better operating efficiency and the contribution from incremental sales.
Chief Technology Officer Neil Boehm said DDR memory remained constrained and circuit-board costs were rising as materials were absorbed by data-center demand. Downing said some individual components had experienced eightfold to tenfold price increases; that was not a measure of inflation across the company’s entire purchasing budget.
Management expects $10 million–$15 million of incremental fourth-quarter costs and anticipates recovering those costs in the first half of 2027. Downing characterized electronics-cost recovery mainly as a timing issue, while noting that precious-metals and other commodity increases were harder to recoup.
Quarterly results show the cost of weaker automotive sales
Third-quarter net sales were $647.7 million, compared with $655.2 million a year earlier. Automotive sales declined to $552.5 million from $573.7 million, with China and the loss of the Volkswagen program weighing on performance.
Premium Audio revenue increased approximately 27% to $54.7 million. Total non-automotive revenue grew about 17% and accounted for 15% of company revenue, up from 12% a year earlier, providing a partial offset to automotive weakness.
Gross margin narrowed to 33.4% from 34.4%, reflecting higher precious-metals costs, unfavorable product mix and reduced operating leverage. Net income fell to $90.6 million from $101 million. Diluted earnings declined to $0.43 from $0.46, although adjusted diluted earnings, a non-GAAP measure, remained at $0.47.
Operating cash flow fell to $83.5 million from $147 million. Inventories reached $550.1 million, compared with $516.3 million at year-end, reflecting higher raw-material balances for electronic components and precious metals.
New manufacturing award has a longer timetable
Gentex secured its first printed circuit board assembly business award with an existing automotive customer. Downing put its annualized value at roughly $180 million, with production expected to begin in 2029. That schedule places the award beyond the maintained 2027 revenue outlook.
The first Dimmable Visor program remains scheduled to start production in the fourth quarter of 2027. Three additional customers were evaluating the product, but management had no further completed deals to announce.
Conclusion
The Gentex outlook preserves a return to revenue growth in 2027, but management’s preliminary margin comments remain cautious. The next test is the fourth quarter of 2026, when the company expects additional component costs before anticipated recovery in the first half of 2027.
Read More News
Disclaimer
This FinanceVelix article provides general information, not personalized financial, investment, legal, or tax advice. Market prices, interest rates and economic conditions can change; investments carry a risk of loss. Facts reflect the material available when published and may change. Check important information independently and consult a qualified professional when needed. Mentioning an asset, company, or service is not an endorsement.



