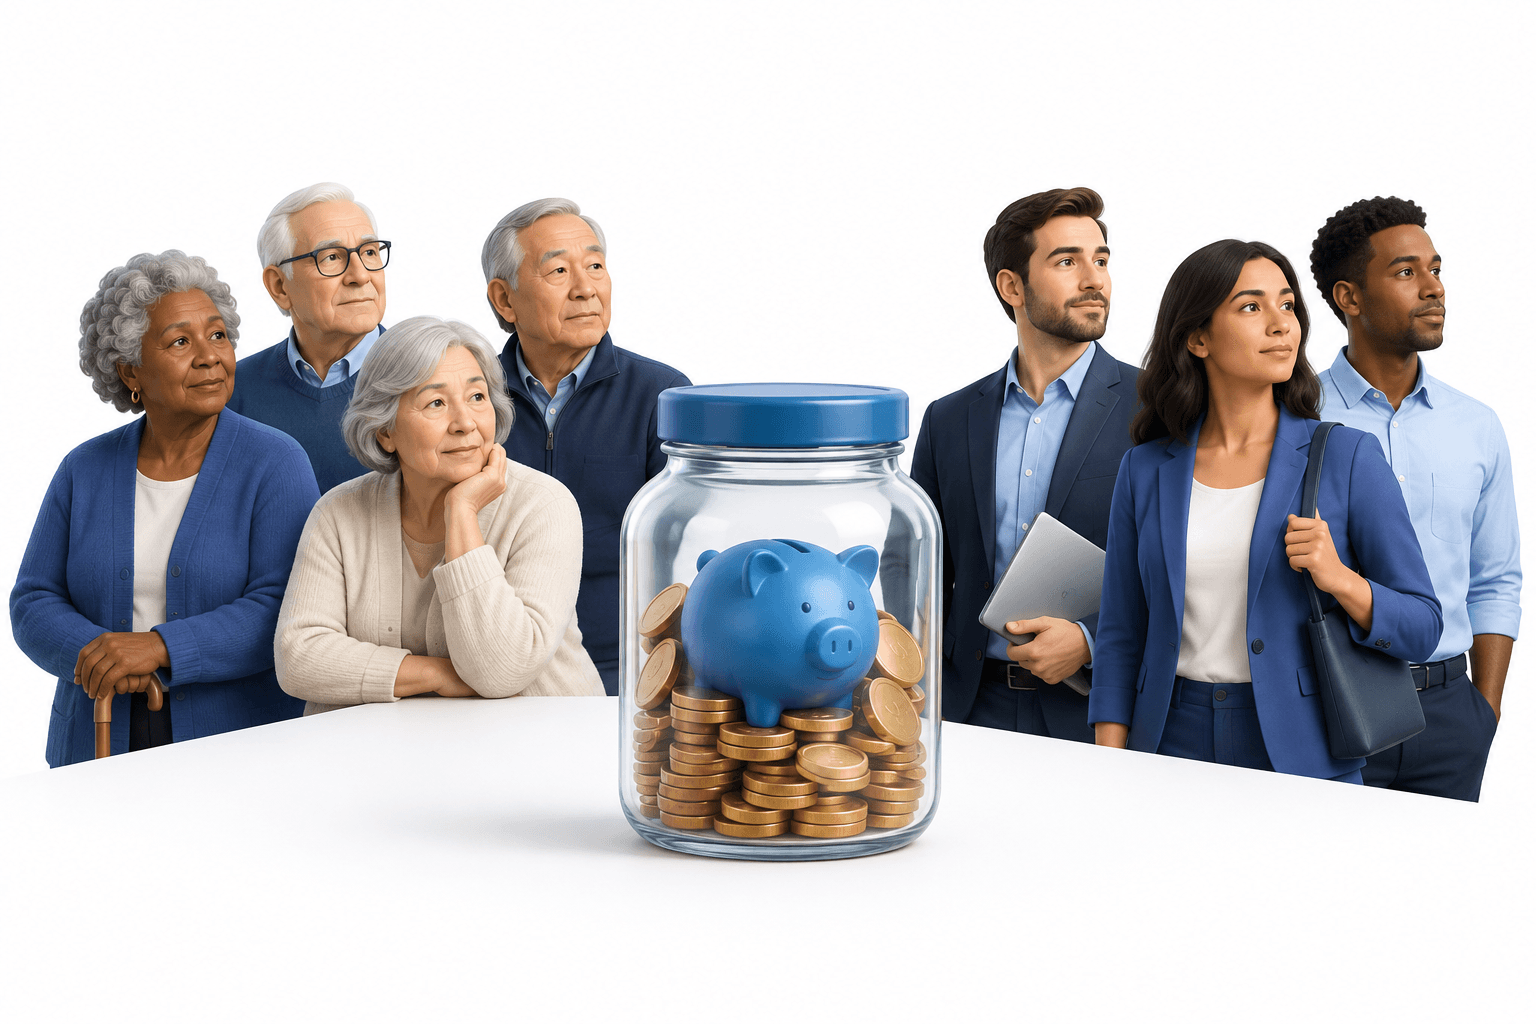
Pension funds and retirement systems are facing growing pressure as people live longer and birth rates fall, increasing the cost of benefits while reducing the pool of workers supporting retirees.
Key Takeaways
- Of 55 pension systems covered by a 2026 index, 43 have fertility rates below the replacement level.
- Pay-as-you-go systems are particularly exposed to a declining ratio of workers to retirees.
- Some funds are taking more investment risk, although managers differ on how much ageing should influence their portfolios.
Why ageing pressures Pension funds
The 2026 Marsh CFA Institute Global Pension Index found that 43 of the 55 systems it covered had fertility rates below the replacement level of 2.1 children per woman. Of those, 23 had rates below 1.5.
Life expectancy at age 65 in more developed regions has increased by 50.9% since 1950, to about 20 additional years. Longer retirements can increase liabilities for defined-benefit plans, which promise a predetermined income. In defined-contribution plans, where payouts depend on savings and investment returns, members face the risk of outliving their savings.
Sebastien Betermier, executive director of the International Centre for Pension Management, said the challenge has become more pronounced over time as funds must cover more years of retirement.
Different funding models face different risks
The pressure is particularly acute for pay-as-you-go systems, in which contributions from current workers largely finance benefits for current retirees. A shrinking workforce can make those commitments harder to support.
Fully funded systems, such as Singapore’s, are more resilient to demographic pressures because benefits are financed through accumulated savings and investments, Betermier said. They are not immune, however: as members retire, benefit payments can exceed incoming contributions, increasing funds’ need for liquid assets and investment returns.
In the United States, the Old-Age and Survivors Insurance Trust Fund is projected to exhaust its reserves in the fourth quarter of 2032, according to its latest trustees’ report.
Investment risk and cash-flow demands
In Australia, about a third of superannuation funds recorded negative natural cash flows from assets over a three-year period, meaning benefit payments exceeded contributions, according to a 2025 Australian Prudential Regulation Authority report.
Some funds have moved toward investments including private equity, infrastructure and private credit as they seek higher returns. Jean-Pierre Aubry of Boston College’s Center for Retirement Research said the extent of that shift varies considerably across markets.
Not all managers view ageing as a reason to take bigger investment risks. Hostplus CEO David Elia said demographic change was one of several factors in investment decisions and emphasized diversification and ensuring potential returns compensate for the risks involved.
Read More News
Disclaimer
This FinanceVelix article provides general information, not personalized financial, investment, legal, or tax advice. Market prices, interest rates and economic conditions can change; investments carry a risk of loss. Facts reflect the material available when published and may change. Check important information independently and consult a qualified professional when needed. Mentioning an asset, company, or service is not an endorsement.
Comments
Be respectful. No spam, impersonation or private credentials. Ordinary posts and comments appear immediately; suspicious links are held for review.
Please wait…