Aya Gold & Silver announced on October 21, 2026, that it had filed the updated Boumadine PEA technical report for its development-stage polymetallic project in Morocco. The assessment models a 14-year mine life and approximately US$3.5 billion in after-tax net present value, but remains preliminary and includes inferred resources that have not demonstrated economic viability.
Key Takeaways
- The filing formalizes assessment results first disclosed on September 9, 2026; it is not a new set of project economics.
- The base case estimates US$463 million in initial capital spending and a 93% after-tax internal rate of return.
- Feasibility work is underway, while Aya’s next scheduled financial update is November 12, 2026.
Table of Contents
- Boumadine PEA filing replaces the previous assessment
- Higher price assumptions support stronger modeled economics
- Mine plan combines open-pit and underground production
- Resource uncertainty remains as feasibility work continues
- Conclusion
Boumadine PEA filing replaces the previous assessment
The technical report was filed on SEDAR+ and EDGAR on October 20, 2026, with an effective date of September 9, 2026. As outlined in Aya’s updated Boumadine assessment announcement, it supersedes the 2025 preliminary economic assessment.
Independent qualified professionals from Lycopodium, CCE Mining and other firms prepared the assessment under Canada’s NI 43-101 mineral-project disclosure standards. Guy Dishaw of SRK Consulting UK prepared the updated mineral resource estimate, effective February 28, 2026.
The distinction between the filing date and the assessment date matters: October’s announcement makes the supporting technical report available rather than introducing newly calculated economic results.
| Item | Details |
|---|---|
| Material in the mine plan | 41.2 million tonnes over the modeled mine life, up 33% from the prior assessment. |
| Indicated resource | 8.6 million tonnes averaging 4.02 grams per tonne gold-equivalent. |
| Inferred resource | 45.4 million tonnes averaging 2.92 grams per tonne gold-equivalent. |
| Modeled cash costs | US$998 per gold-equivalent ounce in years 1–5; US$1,169 over the mine life. |
| Modeled all-in sustaining costs | US$1,105 per gold-equivalent ounce in years 1–5; US$1,300 over the mine life. Both cost measures are non-IFRS and may not be comparable across issuers. |
Higher price assumptions support stronger modeled economics
The base case estimates an after-tax net present value of US$3.537 billion at a 5% discount rate, a 93% internal rate of return and a 0.7-year payback period. It assumes gold at US$3,500 an ounce, silver at US$50 an ounce, zinc at US$1.37 a pound and lead at US$0.90 a pound. All financial amounts are in U.S. dollars.
Aya attributed the improved economic profile to higher commodity-price assumptions, stronger metal payability and a mine life extended from 11 to 14 years. Gold and silver payability—the proportions of contained metal payable in concentrate sales—rose to 82% and 85%, respectively, increases of 12 and eight percentage points.
The assessment’s separate spot-price scenario uses prices from September 3, 2026, not prices at the October filing date. That scenario estimates US$5.525 billion in after-tax net present value and a 128% internal rate of return. The difference illustrates the project’s sensitivity to metal prices; neither scenario represents realized earnings or Aya’s corporate market value.
Mine plan combines open-pit and underground production
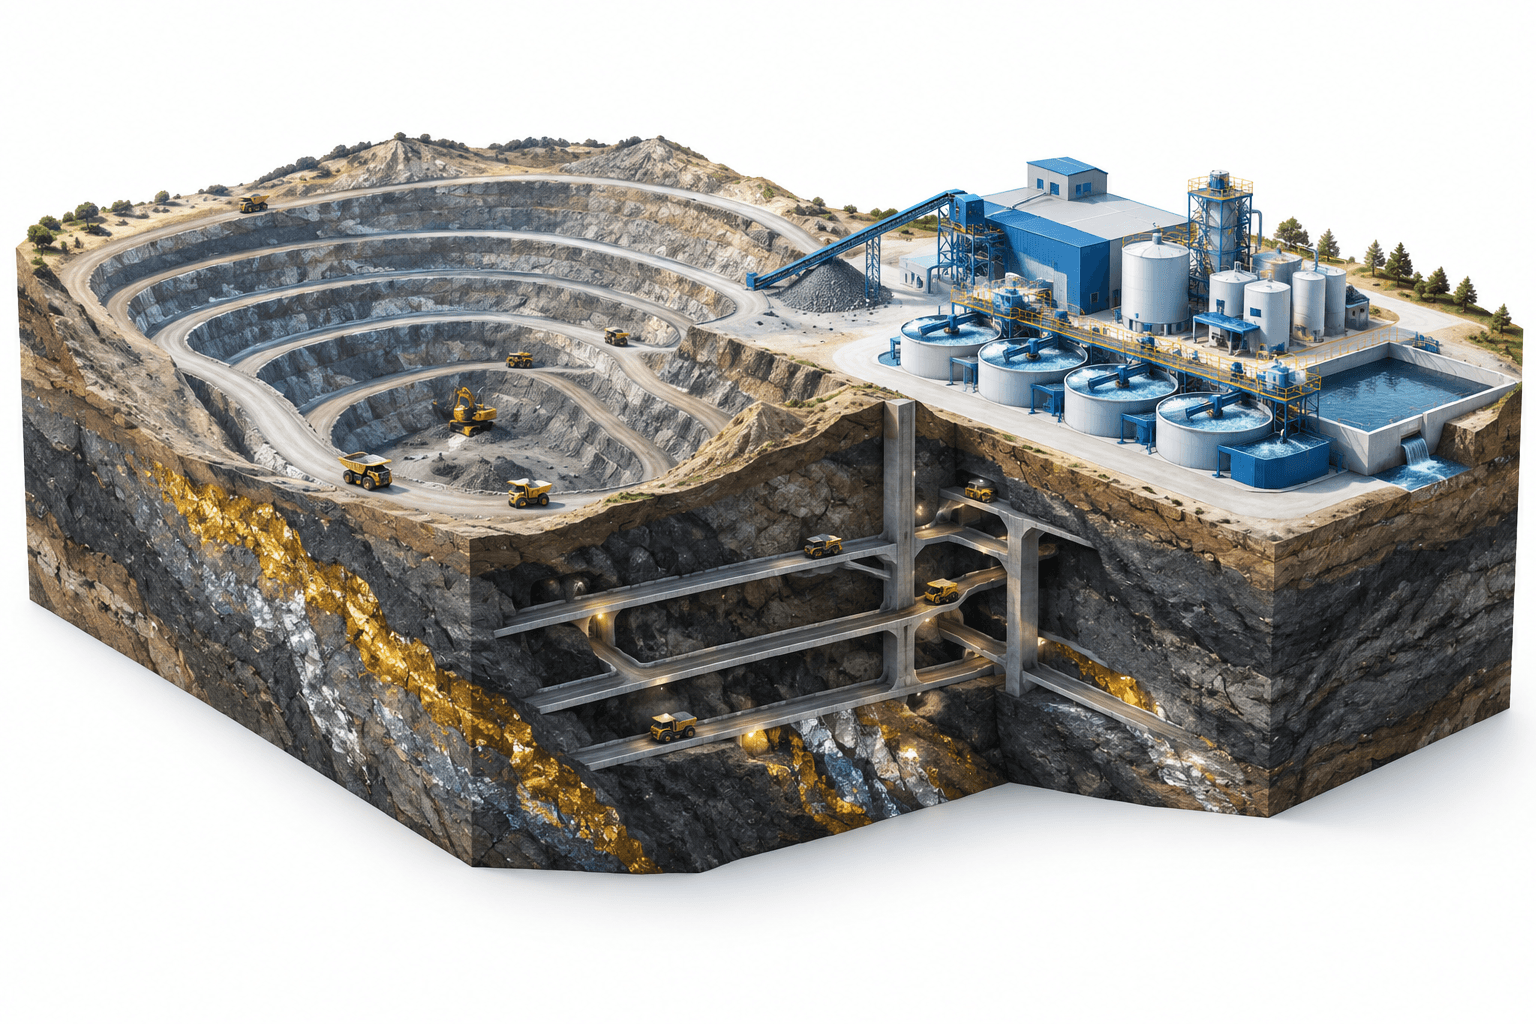
The proposed operation combines open-pit and underground mining with a conventional flotation plant producing zinc, lead and pyrite concentrates. Precious metals would account for most revenue.
The plan estimates average annual production of 348,000 gold-equivalent ounces during the first five years and 271,000 ounces over the mine’s life. Gold-equivalent production combines the modeled value of different metals into a gold-ounce measure using the assessment’s price assumptions.
Estimated lifetime production comprises 2.3 million ounces of gold, 81.2 million ounces of silver, 422,000 tonnes of zinc and 195,000 tonnes of lead. Initial capital spending is estimated at US$463 million, broadly in line with the previous assessment.
Resource uncertainty remains as feasibility work continues
The updated resource estimate contains 1.1 million gold-equivalent ounces in the indicated category, up 34% from the prior estimate, and 4.3 million ounces in the inferred category, up 1%.
Mineral resources are not mineral reserves and do not have demonstrated economic viability. The assessment includes inferred material considered too geologically speculative to qualify as reserves, and Aya cautioned that there is no certainty its projected results will be achieved.
Boumadine has an existing mining license, and feasibility-study work is underway. Those milestones do not turn the preliminary cost, production and return estimates into confirmed operating results.
Conclusion
The filing provides the technical basis for Boumadine’s revised development plan, while feasibility work continues to test the preliminary estimates. Aya’s next confirmed corporate update is its third-quarter results release on November 12, 2026, before market opening, followed by a management call at 10 a.m. ET.
Read More News
Disclaimer
This FinanceVelix article provides general information, not personalized financial, investment, legal, or tax advice. Market prices, interest rates and economic conditions can change; investments carry a risk of loss. Facts reflect the material available when published and may change. Check important information independently and consult a qualified professional when needed. Mentioning an asset, company, or service is not an endorsement.