The Coinbase allegations remain disputed: BlockTower Capital founder Ari Paul has accused the exchange of losing roughly $25 million of his firm’s assets and concealing hacks totaling more than $1 billion across a dozen institutions. Coinbase denies the accusations. On October twentieth, twenty twenty-six, Onramp CEO Michael Tanguma argued that the dispute exposes a separate problem for corporate bitcoin holders: their ability to independently verify assets and control who can move them.
Key Takeaways
- Paul says active litigation prevents him from publishing his evidence; the allegations remain disputed.
- Tanguma argues that corporate custody should provide named users, withdrawal approvals, readable audit trails and independent asset verification.
- His proposed approach distributes signing authority across independent institutions, while acknowledging greater coordination and operational demands.
Table of Contents
- What the Coinbase allegations establish—and do not
- What corporate boards need to verify
- Why asset snapshots are not approval controls
- Distributed custody brings an operational trade-off
What the Coinbase allegations establish—and do not
| Item | Details |
|---|---|
| Alleged BlockTower loss | Paul alleges roughly $25 million of his firm’s assets were lost; Coinbase denies the accusations. |
| Broader concealment allegation | Paul alleges hacks totaling more than $1 billion across a dozen institutions; Coinbase denies the accusations. |
| Public evidence | Paul says active litigation prevents him from publishing his evidence. |
| Proposed governance response | Tanguma advocates independent keyholders, defined approval authority and asset verification by the owner. |
What corporate boards need to verify
Tanguma frames the practical test around familiar treasury responsibilities: identifying who can move assets, who must approve transfers and what happens when someone with credentials leaves, is compromised or dies. An account balance alone does not answer those questions.
Tanguma cites a Deloitte survey of 200 chief financial officers at billion-dollar companies in which accounting and controls complexity registered at 42% as an obstacle to adoption, within a percentage point of price volatility. He argues that custody governance is an adoption issue rather than merely a technical concern.
Tanguma also points to Prime Trust, which discovered in December twenty twenty-one that it could not access legacy wallets. That access problem remained unresolved 18 months later when Nevada moved to place the company into receivership.
Why asset snapshots are not approval controls
Tanguma distinguishes evidence that assets exist at a particular moment from rules governing their subsequent movement. He argues that proof-of-reserves attestations provide a snapshot but do not establish who can authorize a withdrawal tomorrow.
His criticism also extends to reliance on audits, trust charters and controls reports. In his assessment, reviewing a custodian’s processes is not the same as giving a corporate client its own defined roles, withdrawal policies and independent verification capability. The consequence for boards is a need to examine operational authority separately from reported holdings.
Distributed custody brings an operational trade-off
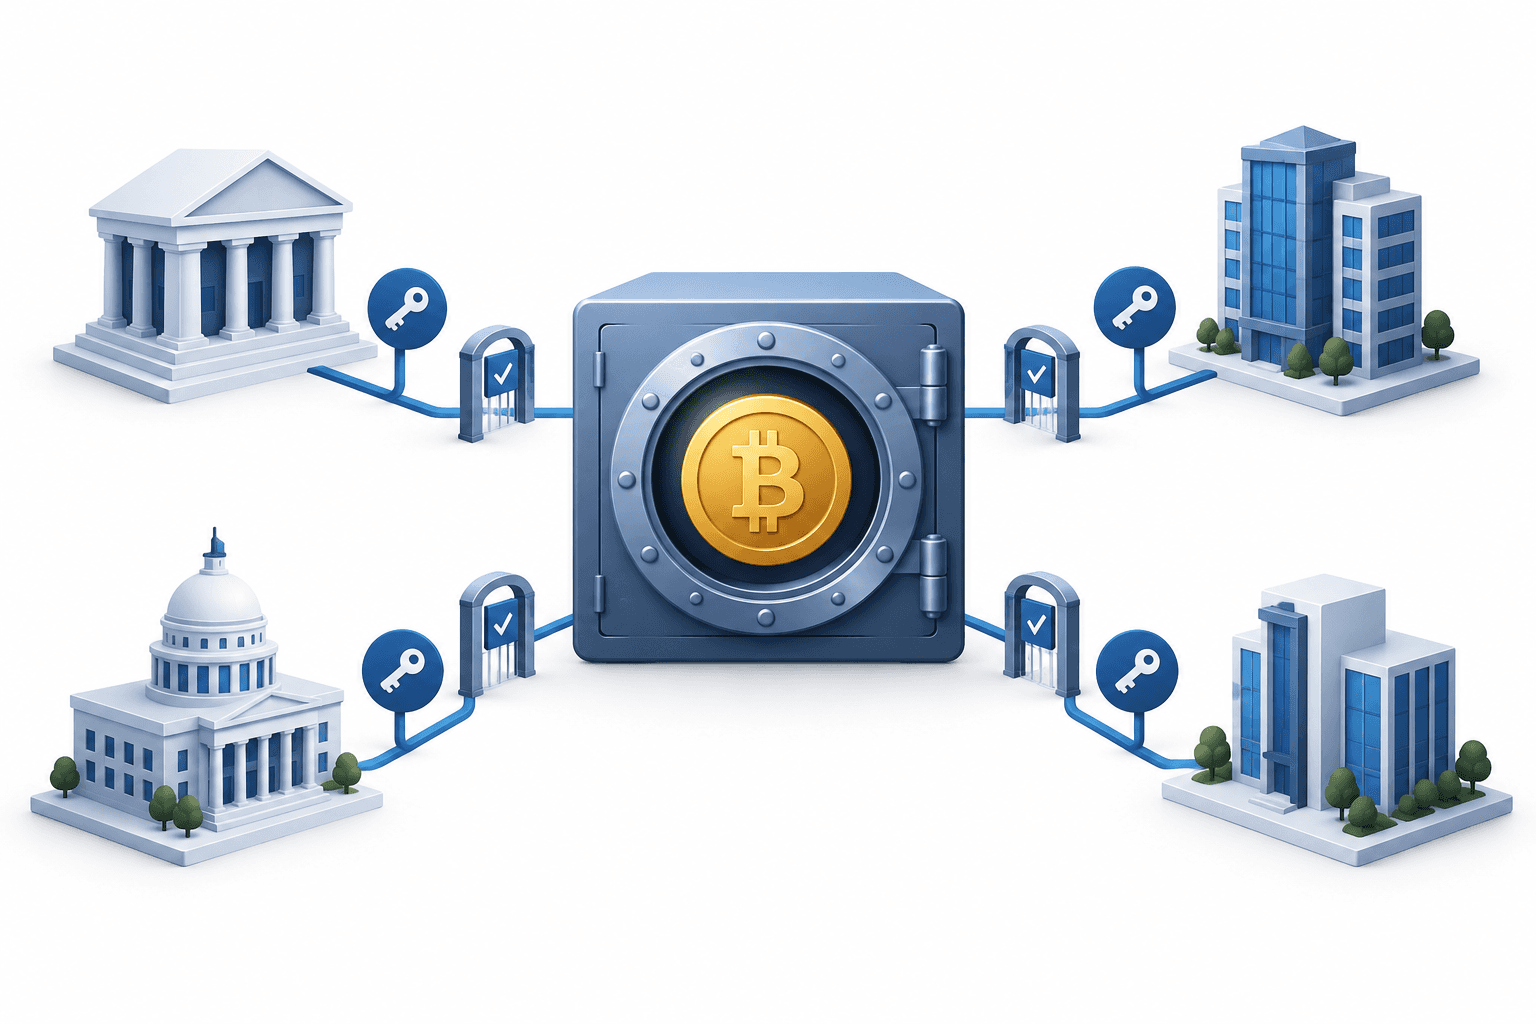
Tanguma advocates arrangements in which independent regulated institutions hold separate signing keys, with no institution able to move assets alone. He pairs that structure with corporate legal ownership, named users, approval policies and an auditable record.
Tanguma cites Morgan Stanley naming separate custodians for its proposed bitcoin ETF as a sign of institutional interest in spreading custody exposure. The proposed arrangement does not establish that his preferred governance model has been fully implemented.
He acknowledges the appeal of a single custodian: fewer counterparties, contracts and integrations. Distributed arrangements require coordination, shared standards and operational discipline. His argument is that those costs should be weighed against whether an owner can verify holdings and maintain control after any individual or institution departs.
Read More News
Disclaimer
This FinanceVelix article provides general information, not personalized financial, investment, legal, or tax advice. Market prices, interest rates and economic conditions can change; investments carry a risk of loss. Facts reflect the material available when published and may change. Check important information independently and consult a qualified professional when needed. Mentioning an asset, company, or service is not an endorsement.