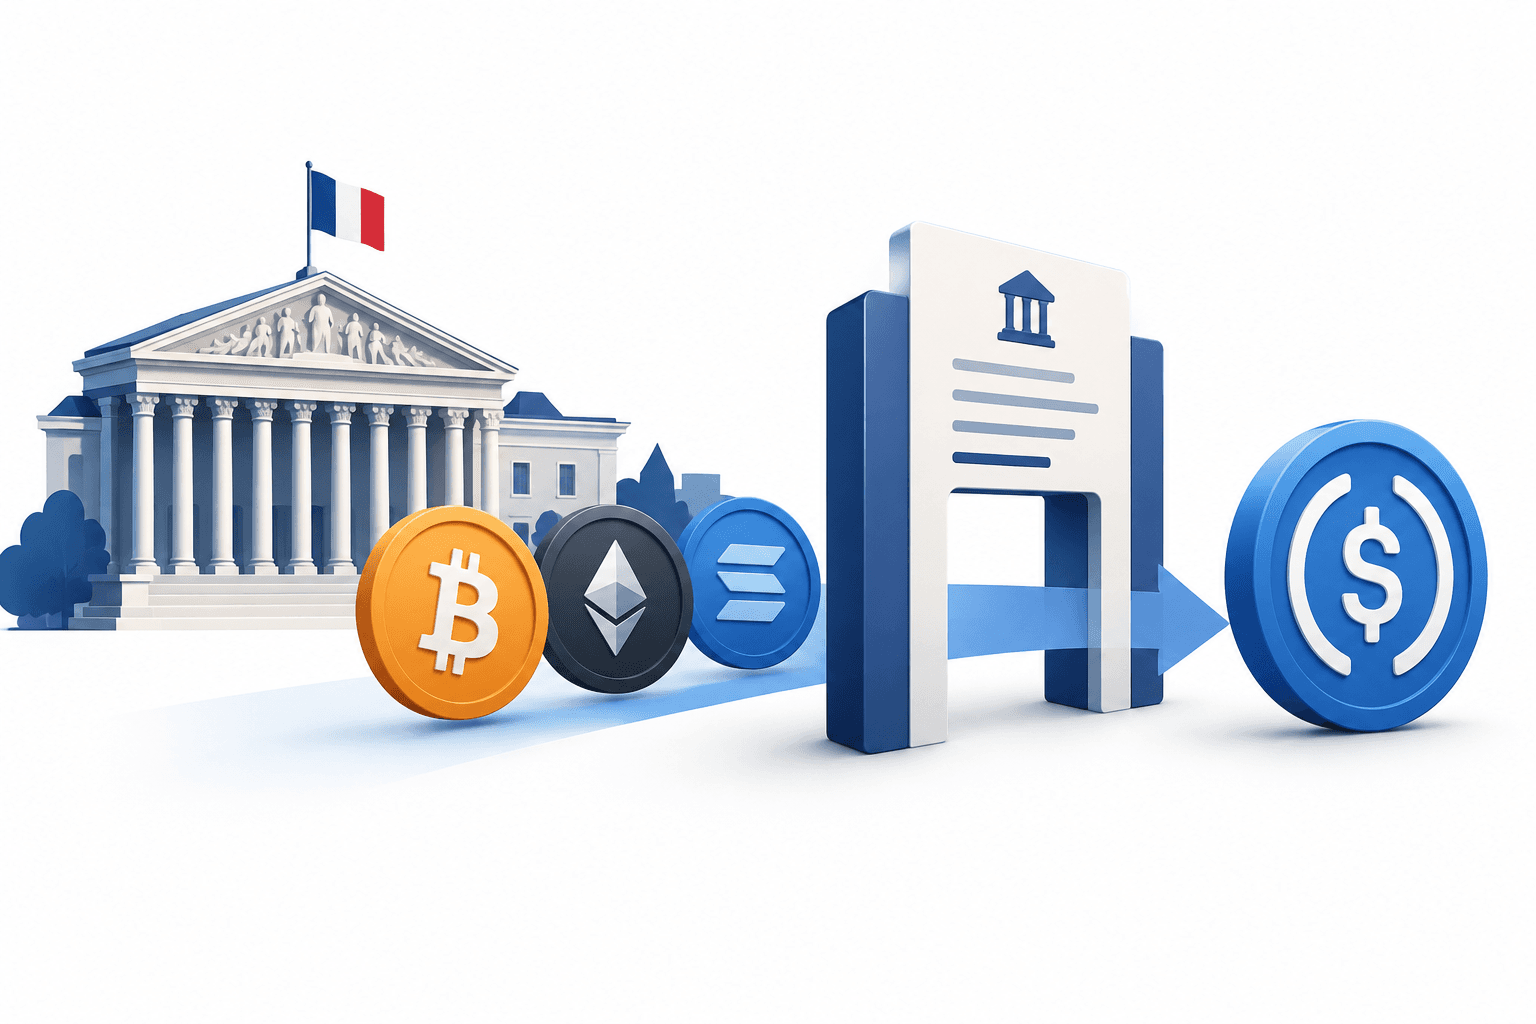
French lawmakers have advanced a proposal that would make gains taxable when investors swap cryptocurrency for qualifying stablecoins, even without cashing out to a bank account. The France stablecoin tax amendment would expose those gains to the default 31.4% capital-gains rate from January 2027, but it still faces further parliamentary stages before becoming law.
Key Takeaways
- The National Assembly approved the budget amendment by 38 votes to 37, with 25 abstentions.
- The proposal would end tax deferral for swaps into e-money tokens defined under the European Union’s MiCA framework.
- The text also changes how gains would be calculated, while officials and industry representatives have raised implementation and trading concerns.
Table of Contents
- What the parliamentary vote changes
- How the France stablecoin tax would affect swaps
- A separate change to calculating gains
- Officials raise implementation and trading concerns
- Conclusion
What the parliamentary vote changes
The National Assembly adopted amendment I-3898 to the 2027 budget on October 16, following earlier approval by its finance committee. The narrow vote moves the proposal forward; it does not establish a final tax rule.
The proposed changes would cover transactions from January 1, 2027. The text could still be amended or removed during the budget’s remaining parliamentary stages.
| Item | Details |
|---|---|
| Crypto-to-crypto exchanges | Generally receive tax deferral under current rules when no additional cash payment is involved. |
| Swaps into MiCA e-money tokens | Would lose that deferral under the amendment, making gains taxable without a fiat withdrawal. |
| Capital-gains calculation | Would shift from a portfolio-wide method to the acquisition cost of assets sold, using weighted averages for identical cryptocurrency units. |
| Legislative status | Approved by the National Assembly but still subject to the budget’s remaining parliamentary stages. |
How the France stablecoin tax would affect swaps
Under current French rules, exchanges between cryptocurrencies generally benefit from tax deferral when there is no additional cash payment. Moving from a cryptocurrency into another qualifying crypto asset therefore does not necessarily trigger immediate taxation of gains.
The amendment would remove that deferral when the asset received is an e-money token as defined by the European Union’s Markets in Crypto-Assets framework, known as MiCA. The proposed trigger is the exchange into a qualifying stablecoin, rather than a subsequent withdrawal into fiat currency.
The distinction matters for investors who move assets into stablecoins while keeping funds within crypto markets: gains could become taxable at that point. The default rate on taxable private-investment gains is 31.4%, although investors can opt for the progressive income-tax scale.
A separate change to calculating gains
The amendment also addresses the calculation of capital gains. It would replace France’s portfolio-wide method with a calculation based on the acquisition cost of the assets sold.
For units of the same cryptocurrency purchased at different prices, the proposed method would use a weighted-average acquisition cost. This makes the calculation change distinct from the stablecoin provision: one determines the cost basis, while the other changes when a swap can trigger tax.
Officials raise implementation and trading concerns
Public Accounts Minister David Amiel asked lawmakers to withdraw the amendment and opposed it otherwise. He questioned the definition of stablecoins and the ability to monitor and trace reallocations within an asset portfolio.
Philippe Juvin, the finance committee’s rapporteur general, favored retaining the deferral because of cryptocurrency volatility.
Francois Volpoet, Chainalysis’ regional sales director for France, warned that the measure could push investors toward decentralized finance platforms, peer-to-peer transactions and offshore exchanges outside international tax-reporting arrangements.
Conclusion
The vote advances a change to both tax timing and gains calculations. Its practical effect still depends on whether the amendment survives the remaining budget process.
Read More News
Disclaimer
This FinanceVelix article provides general information, not personalized financial, investment, legal, or tax advice. Market prices, interest rates and economic conditions can change; investments carry a risk of loss. Facts reflect the material available when published and may change. Check important information independently and consult a qualified professional when needed. Mentioning an asset, company, or service is not an endorsement.