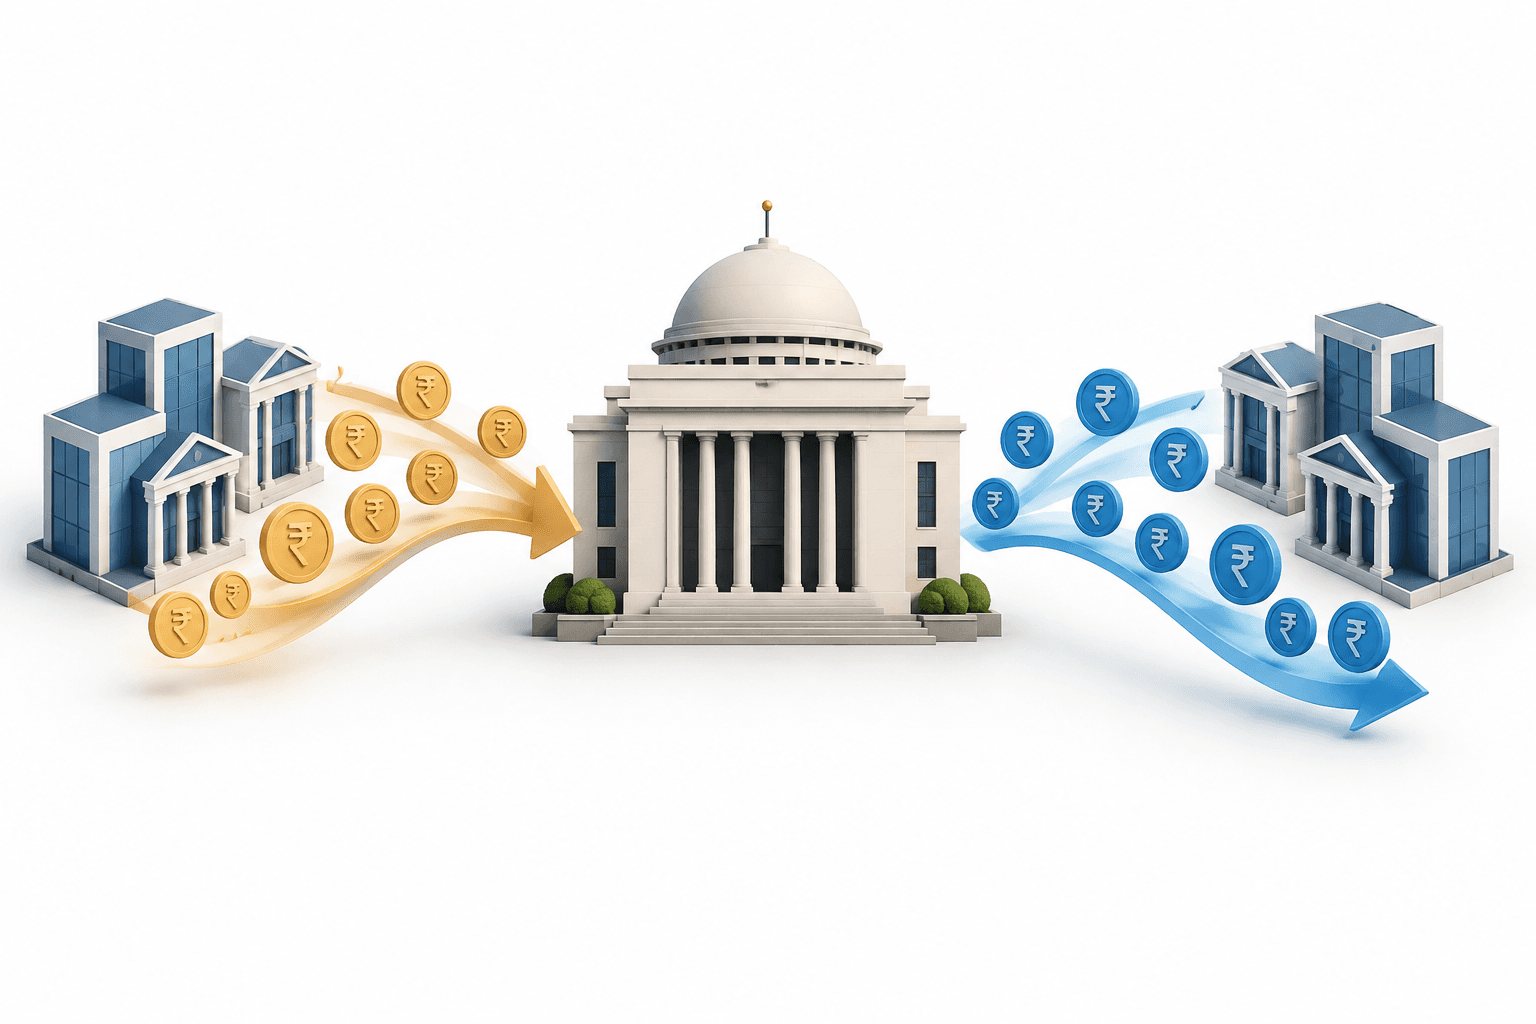
RBI liquidity operations have shifted from absorbing a large banking-system surplus to supplying temporary funds as overnight borrowing costs moved above the policy rate. In the six weeks leading up to October 22, 2026, surplus liquidity fell from a peak of about ₹11 lakh crore to ₹48,303 crore. The subsequent cash injections were intended to limit an overshoot in overnight rates, rather than announce a reversal of monetary policy.
Key Takeaways
- Foreign-currency deposit inflows and swaps with the RBI had sharply increased banks’ rupee liquidity.
- Liquidity absorption helped push overnight borrowing rates from below the policy rate to above it.
- Temporary repo injections addressed higher funding costs while the RBI maintained its tightening stance.
Table of Contents
- RBI liquidity operations target overnight borrowing costs
- Foreign-currency deposits created the initial surplus
- Why temporary cash injections followed
- Conclusion
RBI liquidity operations target overnight borrowing costs
The key to understanding the apparently opposing operations is the weighted average call rate, or WACR: the overnight borrowing rate that the RBI seeks to keep closely aligned with its policy repo rate.
When banks have abundant spare cash, overnight rates can fall below the policy benchmark, weakening the transmission of monetary tightening. If liquidity becomes too tight, those rates can rise above the benchmark instead. Absorbing funds and later providing temporary cash can therefore serve the same operational objective.
The RBI’s explanation of monetary policy transmission describes how changes in short-term interest rates feed into other borrowing costs and influence spending and inflation. That general mechanism explains why money-market conditions matter; the publication is background material, not confirmation of the October 2026 operations.
| Item | Details |
|---|---|
| Variable-rate reverse repo auctions | Used to absorb surplus banking-system liquidity temporarily. |
| September sell-buy swaps | At least $10 billion conducted to drain excess rupee cash. |
| Daily minimum reserve maintenance | Raised from 90% to 99% of required cash reserves. |
| Monday variable-rate repo auction | ₹1 lakh crore operation to provide temporary funds. |
| Friday variable-rate repo operation | ₹50,000 crore operation to provide temporary funds. |
Foreign-currency deposits created the initial surplus
Banks attracted $133 billion from overseas Indians through foreign-currency non-resident bank deposits, known as FCNR(B). They exchanged the dollars with the RBI through a swap facility and received rupee funds in return.
Banking-system surplus liquidity consequently increased from about ₹3.5 lakh crore in August to more than ₹11 lakh crore in September. The WACR fell as low as 4.93% in mid-September.
Rising crude oil prices were also fuelling expectations of a rate increase to contain inflationary pressures. Those expectations were not an announced RBI decision, but the large cash surplus risked keeping market borrowing costs below the level consistent with the central bank’s tightening stance.
The RBI used temporary variable-rate reverse repo auctions, foreign-exchange swaps and a higher daily minimum reserve-maintenance requirement to absorb cash or reduce banks’ flexibility to deploy it.
Why temporary cash injections followed
After the liquidity drain, the WACR rose to 5.75% on October 16, 25 basis points above the 5.50% repo rate. It remained elevated at around 5.65% on October 21.
The RBI then supplied temporary funds through variable-rate repo auctions to prevent overnight rates from rising too sharply. Unlike reverse repo operations, which absorb cash, repo operations provide funds to banks.
The reserve-maintenance change also needs careful interpretation: the increase from 90% to 99% concerned the daily minimum share of required cash reserves that banks must maintain. It did not mean banks had to hold 99% of their deposits as reserves.
Conclusion
The practical test for RBI liquidity management is whether overnight borrowing costs settle closer to the 5.50% policy repo rate. The WACR and the balance between cash-absorbing and cash-providing operations are the next indicators to watch; temporary injections alone do not establish a change in policy stance.
Read More News
Disclaimer
This FinanceVelix article provides general information, not personalized financial, investment, legal, or tax advice. Market prices, interest rates and economic conditions can change; investments carry a risk of loss. Facts reflect the material available when published and may change. Check important information independently and consult a qualified professional when needed. Mentioning an asset, company, or service is not an endorsement.